Navigating the world of college financial aid can often feel like deciphering a complex code. Each year brings its own set of nuances, and the upcoming 2026 FAFSA cycle is no exception. With significant overhauls designed to simplify the application process and expand eligibility, understanding these changes is paramount for students and families aiming to secure crucial funding for higher education. This comprehensive guide will equip you with the knowledge needed to successfully navigate the 2026 FAFSA changes, ensuring you’re well-prepared to maximize your financial aid potential.
The Free Application for Federal Student Aid (FAFSA) is the gateway to billions of dollars in grants, scholarships, work-study funds, and federal student loans. Missing key deadlines or misunderstanding the application can significantly impact your access to these vital resources. This article will break down everything you need to know, from the fundamental shifts in the application form to strategic advice on how to position yourself for the best possible aid package. We’ll delve into the new terminology, revised eligibility calculations, and the importance of timely submission, all designed to demystify the 2026 FAFSA changes.
Understanding the FAFSA Simplification Act: The Foundation of 2026 FAFSA Changes
The landscape of federal student aid is undergoing its most significant transformation in decades, thanks to the FAFSA Simplification Act. This legislative act, passed into law, aims to make the financial aid process easier, more streamlined, and accessible to a broader range of students. While some changes were implemented in the 2024-2025 FAFSA cycle, the full impact and further refinements will be realized in the 2026 FAFSA. These reforms are not just cosmetic; they fundamentally alter how financial need is assessed and how aid is distributed. Students and families need to be aware of these foundational shifts to effectively plan for college costs.
One of the primary goals of the FAFSA Simplification Act is to reduce the complexity and length of the FAFSA form itself. Historically, the FAFSA has been criticized for its numerous questions and often confusing language. The new version is designed to be more intuitive, asking fewer questions and integrating more directly with federal tax data. This integration, through direct data exchange with the IRS, is a cornerstone of the simplification effort, promising a more accurate and less burdensome application experience. This streamlined approach is a major component of the 2026 FAFSA changes and is intended to encourage more students to apply for aid.
Another critical aspect of the Simplification Act is the replacement of the Expected Family Contribution (EFC) with the Student Aid Index (SAI). This change is more than just a name alteration; it represents a fundamental shift in how a student’s financial need is calculated. The SAI uses a revised formula that, for many families, will result in a more equitable assessment of their ability to pay for college. Understanding the SAI and how it differs from the EFC is crucial for anticipating your financial aid eligibility and planning for the costs associated with higher education. We will explore the implications of the SAI in detail later in this guide, highlighting its role in the 2026 FAFSA changes.
Key FAFSA Deadlines for the 2026-2027 Academic Year: Don’t Miss Out!
Deadlines are arguably the most critical component of the financial aid application process. Missing a deadline, even by a day, can mean forfeiting thousands of dollars in potential aid. While federal FAFSA deadlines are typically quite late in the academic year, many states and individual colleges have much earlier deadlines for their own institutional aid. For the 2026-2027 academic year, it’s essential to mark your calendars and understand the multi-tiered deadline structure that governs financial aid applications. Proactive planning is key to successfully navigating the 2026 FAFSA changes.
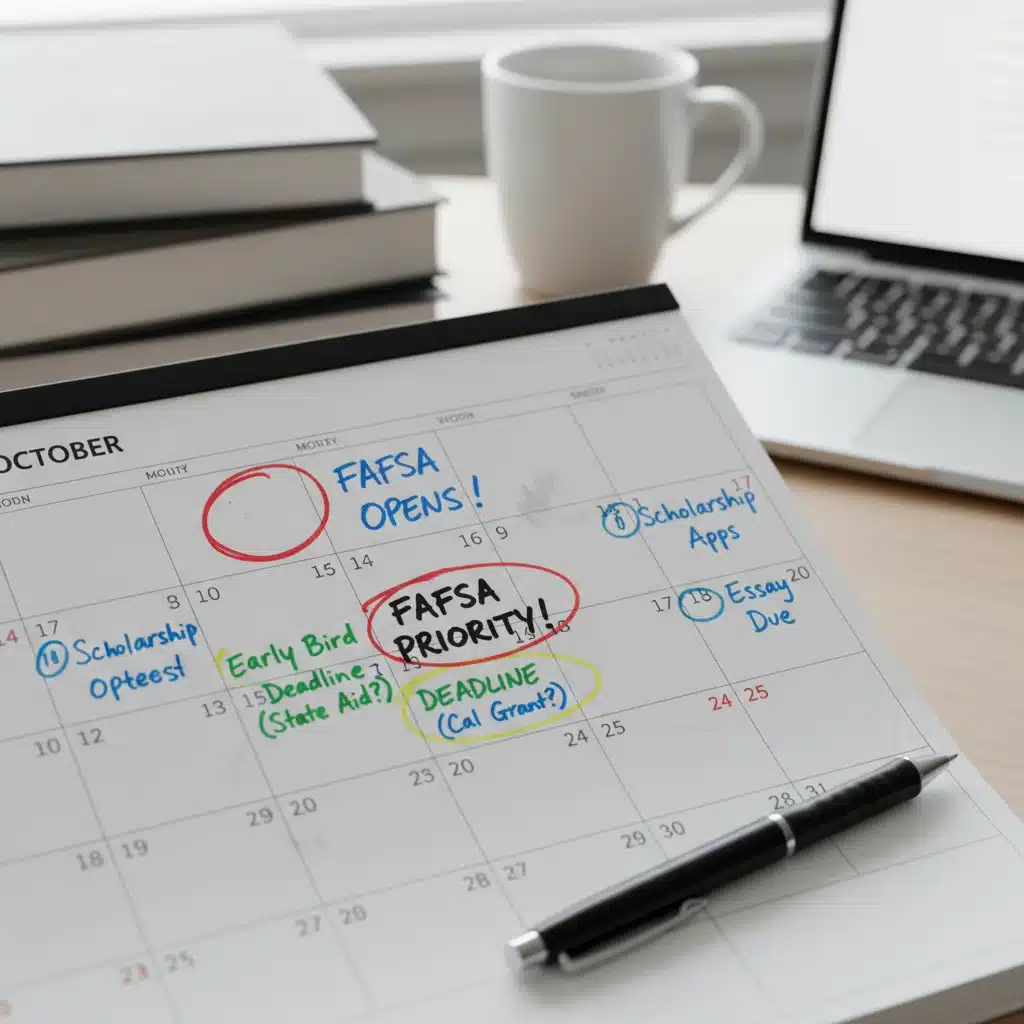
The FAFSA for the 2026-2027 academic year will likely open on October 1, 2025. This is the earliest date you can submit your application. While it might seem early, applying as soon as possible is always recommended. Many types of financial aid, especially grants and scholarships, are distributed on a first-come, first-served basis. Waiting until the last minute can mean that funds have already been depleted, even if you are otherwise eligible. Therefore, aim to complete your FAFSA shortly after it becomes available in October.
Beyond the federal opening date, you must pay close attention to state and institutional deadlines. Each state sets its own FAFSA deadline for state-specific financial aid programs. These can vary widely, from early fall to late spring. Similarly, individual colleges and universities have their own priority deadlines for institutional aid. These deadlines are often much earlier than federal or state deadlines and are crucial for maximizing your aid package. Make a list of all the colleges you are applying to and check their specific financial aid deadlines. Creating a personalized financial aid calendar can be an invaluable tool to manage these various dates and ensure you don’t miss any critical windows related to the 2026 FAFSA changes.
Remember that some deadlines, particularly for institutional aid, might coincide with application deadlines for admission. It’s imperative to treat financial aid deadlines with the same seriousness as admission deadlines. In some cases, applying for financial aid after the priority deadline could result in receiving a less generous aid package, even if you are admitted to the institution. Staying organized and informed about these crucial dates will be a significant factor in your success with the 2026 FAFSA changes.
The Shift from EFC to Student Aid Index (SAI): What It Means for You
One of the most significant and impactful 2026 FAFSA changes is the replacement of the Expected Family Contribution (EFC) with the Student Aid Index (SAI). While both are designed to measure a family’s ability to contribute to college costs, the SAI introduces several key differences that can affect a student’s aid eligibility. Understanding these differences is crucial for accurately estimating your potential financial aid and planning for college expenses.
The EFC, which has been in use for decades, was calculated using a complex formula that often led to confusion and sometimes seemed to overestimate a family’s true financial capacity. The new SAI aims to be a more transparent and equitable measure. A major change is that the SAI can now be a negative number, down to -1500. This doesn’t mean a student will receive $1,500 in aid directly, but rather it indicates a higher level of financial need, potentially qualifying them for maximum Pell Grant eligibility and other need-based aid. This is a crucial distinction for low-income families, as it broadens the scope of demonstrated need.
Another notable difference in the SAI calculation involves the treatment of family size and multiple children in college. Under the EFC formula, having multiple children enrolled in college simultaneously significantly lowered the EFC per child, often leading to more aid. The new SAI calculation, however, eliminates this benefit. While the FAFSA will still ask about the number of children in college, this information will not directly impact the SAI calculation in the same way it did with the EFC. This particular change may have a significant impact on middle- and upper-income families with multiple children pursuing higher education, potentially leading to a decrease in their overall need-based aid. This is a critical aspect of the 2026 FAFSA changes to consider.
Furthermore, the SAI calculation places greater emphasis on federal poverty guidelines, making it more responsive to the financial realities of low-income families. Income protection allowances have also been adjusted to be more generous, shielding more of a family’s income from the aid calculation. These adjustments are designed to expand Pell Grant eligibility and provide more targeted support to students with the greatest financial need. For many, the transition to SAI will result in a more accurate reflection of their financial situation and potentially an increase in their eligibility for various forms of financial aid. Familiarizing yourself with the nuances of the SAI is essential for navigating the 2026 FAFSA changes effectively.
New Terminology and Simplified Application Process for 2026 FAFSA
Beyond the EFC-to-SAI transition, the 2026 FAFSA changes introduce several new terms and a significantly streamlined application process. These updates are all part of the broader effort to make financial aid more accessible and less intimidating. Understanding this new terminology and the improved application flow will help you complete the FAFSA accurately and efficiently.
One of the most impactful changes is the direct data exchange with the IRS. Previously, applicants had to manually transfer tax information using the IRS Data Retrieval Tool (DRT), which could sometimes be cumbersome. Now, all applicants and contributors (students, parents, and spouses, if applicable) will be required to provide consent for the Department of Education to retrieve their tax information directly from the IRS. This mandatory consent ensures a smoother, more secure, and more accurate transfer of financial data, significantly reducing the potential for errors and the need for manual input. This automation is a cornerstone of the simplified application process under the 2026 FAFSA changes.
The FAFSA will also introduce the concept of ‘Contributors.’ A contributor is anyone required to provide information on the FAFSA, which typically includes the student, their parents (if dependent), and their spouse (if married). Each contributor will receive an invitation to complete their specific section of the FAFSA and will need their own Federal Student Aid (FSA) ID. This change aims to clarify who needs to provide information and streamline the process for each individual, ensuring that all necessary data is collected efficiently. Understanding who your contributors are and ensuring they all have an FSA ID will be a key step in preparing for the 2026 FAFSA changes.
Furthermore, the number of questions on the FAFSA form has been substantially reduced. The new form is projected to have significantly fewer questions than its predecessors, making it quicker and easier to complete. Many questions that were previously confusing or redundant have been removed. This reduction in complexity is a direct result of the FAFSA Simplification Act’s goal to make the application more user-friendly and less of a barrier to accessing financial aid. The combination of direct data exchange, clearer contributor roles, and fewer questions will make the 2026 FAFSA changes a welcome improvement for many applicants.
Expanding Pell Grant Eligibility and Other Aid Opportunities
A major focus of the FAFSA Simplification Act, and consequently the 2026 FAFSA changes is to expand eligibility for federal student aid, particularly the Pell Grant. The Pell Grant is a cornerstone of federal financial aid, providing need-based grants that do not have to be repaid. The revised eligibility criteria and the new Student Aid Index (SAI) are designed to make Pell Grants accessible to more students, especially those from low-income backgrounds.
Under the new system, Pell Grant eligibility will be tied more directly to the federal poverty level. Students whose Student Aid Index (SAI) is negative or very low will automatically qualify for the maximum Pell Grant. Additionally, a new provision allows for minimum Pell Grant eligibility for students whose SAI is above zero but below a certain threshold, provided their family income is within 175% of the federal poverty level (or 225% for single-parent households). This expansion ensures that more students receive at least some Pell Grant funding, broadening access to higher education for those who need it most. This is a significant positive outcome of the 2026 FAFSA changes.
Beyond Pell Grants, the simplified FAFSA and the new SAI calculation will also impact eligibility for other forms of federal aid, including subsidized student loans, federal work-study, and other campus-based aid programs. Because these programs are also need-based, a lower SAI will generally lead to greater eligibility. It’s important to remember that while the FAFSA determines your eligibility for federal aid, colleges use this information to package their own institutional grants and scholarships. Therefore, a more favorable SAI can open doors to a wider range of financial assistance from both federal and institutional sources.
Students should also be aware that some state aid programs are directly linked to federal Pell Grant eligibility. As Pell Grant eligibility expands, so too might access to state-specific grants and scholarships. This ripple effect means that the 2026 FAFSA changes could have a far-reaching positive impact on the overall financial aid landscape for many students. It underscores the importance of completing the FAFSA, even if you think you might not qualify, as eligibility criteria are shifting in a more inclusive direction.
Maximizing Your Aid Potential: Strategies for the 2026 FAFSA
With the 2026 FAFSA changes on the horizon, proactive strategies are more important than ever to maximize your financial aid potential. It’s not just about filling out the form; it’s about understanding the nuances and making informed decisions that can positively impact your aid package.
1. Apply Early, Every Year
As mentioned, submitting your FAFSA as soon as it opens on October 1st is crucial. Many grants, scholarships, and even some federal work-study funds are limited and awarded on a first-come, first-served basis. Even if your college’s priority deadline is later, getting your application in early ensures you’re at the front of the line for available funds. This simple step can significantly increase your chances of receiving a more generous aid package, especially with the 2026 FAFSA changes emphasizing efficiency.
2. Understand the Student Aid Index (SAI)
Familiarize yourself with how the SAI is calculated and how it differs from the old EFC. While you can’t drastically alter your family’s income or assets, understanding the factors that influence your SAI can help you anticipate your eligibility. Be aware of how the elimination of the multiple-children-in-college discount might affect your family’s aid eligibility if you have siblings attending college simultaneously. This knowledge is power when navigating the 2026 FAFSA changes.
3. Complete All Sections Accurately and Completely
Errors or omissions are common reasons for delayed processing or reduced aid. Double-check all information, especially social security numbers, dates of birth, and income figures. The direct data exchange with the IRS should minimize tax-related errors, but ensure that you and all contributors provide consent for this data retrieval. Any discrepancies could flag your application for verification, delaying your aid. Accuracy is paramount with the 2026 FAFSA changes.
4. Communicate with Your College’s Financial Aid Office
Don’t hesitate to reach out to the financial aid offices of the colleges you’re interested in. They are your best resource for understanding institutional deadlines, specific aid programs, and how the 2026 FAFSA changes will impact their aid packaging policies. If your family has experienced a significant change in financial circumstances (e.g., job loss, medical expenses, divorce) since the tax year used on your FAFSA, inform the financial aid office. They may be able to make professional judgment adjustments to your aid package.
5. Explore All Types of Aid
The FAFSA is primarily for federal aid, but don’t stop there. Research scholarships from private organizations, local community groups, and your high school. Many scholarships are not need-based and can significantly supplement your financial aid package. The more diverse your approach to funding, the stronger your overall financial support will be. While the FAFSA is central, it’s part of a larger financial aid ecosystem, especially with the evolving 2026 FAFSA changes.
6. Understand the Impact of Assets
While the SAI calculation generally offers more generous income protection, it still considers assets. Some assets are excluded (e.g., primary residence, retirement accounts), but others, like savings accounts, investments, and 529 college savings plans, are assessed. If possible, strategic planning regarding asset allocation can sometimes help, but always consult with a financial advisor for personalized advice. Being mindful of your assets is a key part of navigating the 2026 FAFSA changes.
7. Keep Records
Maintain organized records of all your financial aid applications, correspondence with financial aid offices, and any documents you submit. This includes copies of your FAFSA, tax returns, and any follow-up information requested. Good record-keeping will be invaluable if questions arise or if you need to appeal an aid decision. This due diligence is always important, but especially so with the new 2026 FAFSA changes.
Common Misconceptions and Clarifications about the 2026 FAFSA
With significant reforms like the 2026 FAFSA changes, it’s common for misconceptions to arise. Addressing these directly can help students and families avoid pitfalls and ensure they have accurate information as they navigate the financial aid process.
Misconception 1: My family earns too much money to qualify for aid.
Clarification: This is one of the most persistent myths. Many families mistakenly believe they won’t qualify for federal aid due to their income. However, the FAFSA determines eligibility for various types of aid, including unsubsidized federal student loans, which are available regardless of financial need. Furthermore, changes to the SAI calculation and expanded Pell Grant eligibility mean that more families may qualify for need-based aid than before. Always complete the FAFSA, as you never know what you might be eligible for. The 2026 FAFSA changes are specifically designed to broaden access.
Misconception 2: My parents own a home, so we won’t get aid.
Clarification: The value of your primary residence is NOT counted as an asset in the FAFSA calculation. This has been a long-standing rule and remains true under the 2026 FAFSA changes. So, owning a home does not automatically disqualify you from receiving financial aid. Other assets, like investments or savings accounts, are considered, but your family home is protected.
Misconception 3: The FAFSA is only for federal aid; it doesn’t matter for scholarships.
Clarification: While the FAFSA is the gateway to federal aid, many colleges and universities use FAFSA data to determine eligibility for their own institutional grants and scholarships. Additionally, some private scholarship providers may require a completed FAFSA to assess a student’s financial need. Therefore, completing the FAFSA is often a prerequisite for a wide array of financial aid opportunities, not just federal ones. Don’t underestimate its importance, especially with the new rules from the 2026 FAFSA changes.
Misconception 4: I only need to fill out the FAFSA once.
Clarification: The FAFSA must be completed every year you plan to attend college and wish to receive federal financial aid. Your financial situation can change from year to year, and so can the aid formulas. Reapplying annually ensures that your aid package accurately reflects your current financial need and that you continue to receive all eligible funding. Make annual FAFSA submission a routine part of your college planning, adapting to any new 2026 FAFSA changes or subsequent updates.
Misconception 5: I should wait until I’m accepted to a college to complete the FAFSA.
Clarification: This is a common mistake that can lead to missed deadlines and lost aid. You should complete the FAFSA as soon as it becomes available (October 1st) for the academic year you plan to attend, even if you haven’t decided on a college or received acceptance letters. You can list up to 20 colleges on your FAFSA, and you can update this list later if your plans change. Prioritizing early submission is key to maximizing your aid, particularly with the competitive nature of some funds and the phased rollout of the 2026 FAFSA changes.
Preparing for the Future: Beyond the 2026 FAFSA
While this guide focuses on the immediate 2026 FAFSA changes, it’s important to remember that financial aid policies are dynamic. The FAFSA Simplification Act has laid the groundwork for a more accessible system, but continuous vigilance and adaptation will be necessary for future academic years. Staying informed about any subsequent legislative changes or policy updates from the Department of Education is crucial for long-term financial planning for higher education.
One key aspect of future preparedness involves cultivating good financial habits early on. For students, understanding personal finance, budgeting, and the implications of student loan debt are invaluable life skills. For parents, continued strategic financial planning, including saving for college through appropriate vehicles like 529 plans, remains a cornerstone of supporting their children’s educational aspirations. The 2026 FAFSA changes are a step towards simplification, but they do not eliminate the need for careful financial stewardship.
Engaging with high school counselors and college financial aid advisors regularly will also provide ongoing support and up-to-date information. These professionals are often the first to receive updates on policy changes and can offer personalized guidance based on your unique circumstances. Building a relationship with these resources can prove invaluable as you navigate not only the 2026 FAFSA changes but also any future modifications to the financial aid landscape.
Finally, remember that education is an investment. While the cost can be daunting, the opportunities it unlocks are often immeasurable. By diligently understanding and applying for financial aid, utilizing the resources available, and adapting to changes like the 2026 FAFSA reforms, you are taking a significant step towards making higher education an attainable reality. Embrace the changes, stay informed, and commit to securing the financial support you need to achieve your academic and career goals.
Conclusion: Embracing the 2026 FAFSA Changes for a Brighter Future
The 2026 FAFSA changes represent a pivotal moment in federal student aid, promising a more streamlined, equitable, and accessible path to college funding. From the transition to the Student Aid Index (SAI) and the elimination of complex questions to the direct data exchange with the IRS, these reforms are designed to benefit a wider array of students and families. While change can sometimes feel daunting, understanding these updates is your strongest tool for maximizing your financial aid potential.
We’ve covered the critical aspects: the foundational FAFSA Simplification Act, the absolute necessity of adhering to strict deadlines, the implications of the SAI replacing the EFC, and the expanded opportunities for Pell Grants and other forms of aid. Moreover, we’ve outlined actionable strategies to help you navigate the application process successfully, from applying early to understanding common misconceptions.
By taking a proactive and informed approach, you can confidently tackle the 2026 FAFSA changes. Start by gathering your necessary documents, securing your FSA ID, and marking those crucial deadlines on your calendar. Don’t hesitate to reach out to financial aid professionals for personalized guidance. The goal of these reforms is to ensure that financial barriers do not prevent deserving students from pursuing higher education. Embrace these changes, empower yourself with knowledge, and pave the way for a successful academic journey. Your future starts with a completed FAFSA.