The 2026 Impact of Automation on Personal Financial Wellness: Recent Updates and Future Outlook
In an era defined by rapid technological advancement, the landscape of personal finance is undergoing a monumental transformation. The pervasive influence of automation, artificial intelligence (AI), and machine learning (ML) is not merely a futuristic concept; it is a present reality that is actively reshaping how individuals manage, grow, and perceive their financial well-being. As we look towards 2026, the automation financial wellness paradigm is poised to reach new heights, offering unprecedented opportunities for efficiency, accessibility, and personalized financial guidance.
This comprehensive article delves into the multifaceted impact of automation on personal financial wellness, exploring the recent updates and anticipating the future trajectory of this profound shift. We will examine how automated tools are empowering individuals to take control of their financial destinies, from streamlining mundane tasks to providing sophisticated investment insights. Understanding these changes is crucial for anyone seeking to navigate the evolving financial ecosystem and harness the power of technology for a more secure and prosperous future.
The Rise of Automated Financial Management: A New Era of Efficiency
The core promise of automation in personal finance is efficiency. Gone are the days of manual budgeting, tedious transaction tracking, and complex investment calculations. Automated financial management tools are designed to simplify these processes, making financial health more attainable for everyone, regardless of their financial acumen or available time. By 2026, these tools will be even more sophisticated, intuitive, and integrated into our daily lives.
Automated Budgeting and Expense Tracking: Beyond Basic Spreadsheets
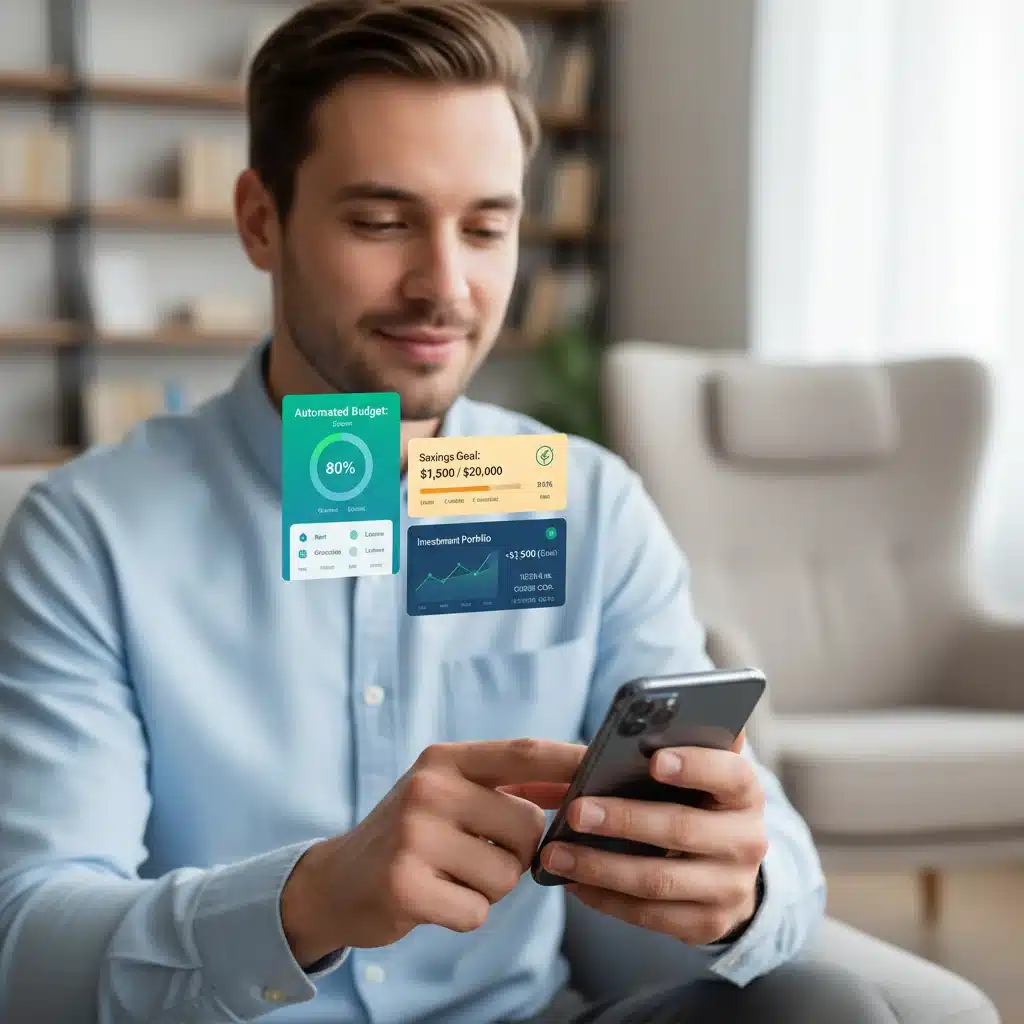
Budgeting, often seen as a chore, is being revolutionized by automation. Modern budgeting apps leverage AI to automatically categorize transactions, track spending patterns, and provide real-time insights into financial habits. These tools learn from user behavior, offering personalized recommendations for saving and identifying areas where expenses can be cut. By 2026, we can expect these systems to predict future spending with remarkable accuracy, factoring in seasonal variations, upcoming bills, and even personal goals like vacation planning or large purchases. The integration with smart home devices and voice assistants will also become more seamless, allowing users to query their financial status or make budgeting adjustments with simple voice commands, further enhancing the automation financial wellness experience.
Furthermore, these automated budgeting platforms are moving beyond simple expense tracking to incorporate predictive analytics. Imagine an app that not only tells you what you’ve spent but also proactively warns you about potential cash flow issues in the coming weeks, suggesting adjustments to avoid overdrafts or missed payments. This proactive approach empowers individuals to make informed decisions before problems arise, significantly reducing financial stress. The ability to set up automated rules for savings, such as automatically transferring a percentage of each paycheck into a dedicated savings account, will become standard, fostering consistent saving habits without conscious effort.
Robo-Advisors: Democratizing Investment Access
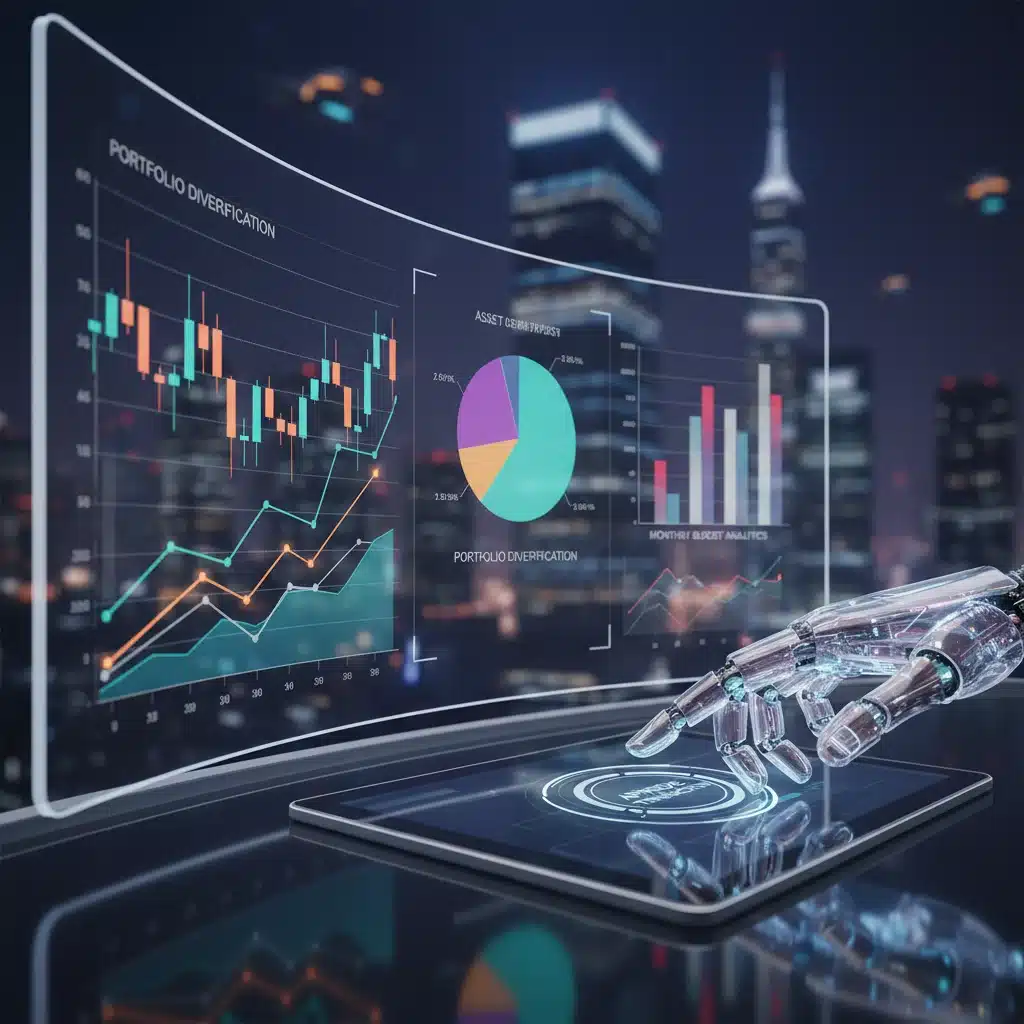
Perhaps one of the most significant advancements in automation financial wellness is the proliferation of robo-advisors. These automated platforms use algorithms to manage investment portfolios based on an individual’s financial goals, risk tolerance, and time horizon. They offer diversified portfolios, rebalancing services, and tax-loss harvesting, all at a fraction of the cost of traditional human financial advisors.
By 2026, robo-advisors will be even more sophisticated, incorporating advanced AI to adapt to rapidly changing market conditions and individual life events. They will offer hyper-personalized investment strategies, potentially even integrating with other automated financial tools to provide a holistic view of an individual’s financial picture. This democratization of high-quality investment advice is crucial for closing the wealth gap and enabling more people to build long-term financial security. The continuous learning capabilities of these AI-driven platforms mean they will become increasingly adept at identifying nuanced market trends and optimizing portfolios for maximum returns while adhering to an individual’s specific risk profile. This evolution will make sophisticated investment strategies accessible to a broader audience, fostering greater financial inclusion.
The Evolving Landscape of Personal Financial Planning
Automation isn’t just about managing money; it’s about transforming the entire process of personal financial planning. From debt management to retirement planning, automated tools are providing more comprehensive and accessible solutions.
Automated Debt Management and Repayment Strategies
Debt can be a significant impediment to financial wellness. Automated tools are emerging to help individuals tackle debt more effectively. These platforms can analyze various debts (credit cards, student loans, mortgages), recommend optimal repayment strategies (e.g., snowball or avalanche methods), and even automate payments. By 2026, we can anticipate more sophisticated AI-driven debt management systems that can negotiate with creditors on behalf of consumers, identify opportunities for refinancing, and dynamically adjust repayment plans based on income fluctuations or unexpected expenses. This level of proactive and adaptive debt management will be a game-changer for many, significantly reducing the burden of debt and accelerating the path to financial freedom, thereby enhancing automation financial wellness for millions.
These systems will also incorporate behavioral economics principles to encourage better debt habits. For instance, they might send personalized nudges or celebrate small repayment milestones to keep users motivated. The ability to visualize the impact of different repayment scenarios – how much interest saved, how much sooner debt-free – will be a powerful motivator. Moreover, integration with credit reporting agencies will allow these tools to provide real-time updates on credit scores and offer advice on improving them, creating a virtuous cycle of financial improvement.
Retirement Planning and Long-Term Goal Setting
Planning for retirement and other long-term goals often feels overwhelming. Automated financial planning tools are simplifying this complex process. By inputting goals, current savings, and risk tolerance, these platforms can project future outcomes, illustrate the impact of different saving rates, and recommend adjustments. In the near future, these tools will leverage AI to account for a wider range of variables, including potential career changes, healthcare costs, and inflation rates, providing more realistic and adaptable long-term financial roadmaps.
These AI-powered planners will go beyond simple projections, offering dynamic scenario analysis. Users will be able to explore ‘what-if’ scenarios, such as the impact of an early retirement, a significant inheritance, or unexpected medical expenses, on their long-term financial health. The integration of predictive analytics will also allow these platforms to anticipate changes in economic conditions and recommend adjustments to investment strategies or savings plans accordingly. This forward-looking and adaptive approach will empower individuals to make more confident and resilient financial plans, solidifying the role of automation financial wellness in securing future prosperity.
Challenges and Considerations in an Automated Financial World
While the benefits of automation financial wellness are undeniable, it’s crucial to acknowledge the challenges and considerations that come with this technological shift. Addressing these concerns is vital for ensuring that automation serves to uplift, rather than disadvantage, individuals.
Data Privacy and Security Concerns
The reliance on automated financial tools necessitates sharing sensitive personal financial data. This raises significant concerns about data privacy and security. As automation becomes more integrated, the need for robust cybersecurity measures and transparent data handling policies will become paramount. Individuals must be educated on how their data is used, protected, and stored, and financial institutions must continually invest in cutting-edge security protocols to prevent breaches and maintain user trust. Regulations like GDPR and CCPA are just the beginning; by 2026, we can expect even stricter global standards for financial data protection, which will be essential for widespread adoption and trust in automated financial services.
Furthermore, the onus will be on users to choose reputable platforms with strong security track records. Understanding encryption, two-factor authentication, and privacy settings will become as important as understanding one’s credit score. The industry will likely see the emergence of independent auditors specializing in financial AI security, providing certifications and ratings to help consumers make informed choices. This focus on security and privacy is not just a technical challenge but a fundamental building block for the continued growth of automation financial wellness solutions.
The Digital Divide and Financial Inclusion
The benefits of automation are largely dependent on access to technology and digital literacy. This creates a potential digital divide, where individuals without reliable internet access, smartphones, or the necessary technical skills may be left behind. Ensuring that automated financial tools are accessible and understandable to all segments of the population, including the elderly and those in underserved communities, is a critical challenge. Efforts must be made to provide digital literacy programs and develop user interfaces that are intuitive and easy to navigate for everyone, bridging the gap to truly achieve universal automation financial wellness .
Governments and non-profit organizations will play a crucial role in promoting digital inclusion, perhaps through subsidized internet access or community-based training programs. Financial institutions also have a responsibility to design inclusive products, potentially offering simpler, text-based interfaces for basic services or partnering with community centers to provide hands-on assistance. The goal should be to leverage automation to reduce barriers to financial services, not create new ones. Without addressing this divide, the promise of automation will remain out of reach for a significant portion of the global population.
The Need for Human Oversight and Financial Literacy
While automation can handle many financial tasks, it cannot entirely replace human judgment and critical thinking. Financial literacy remains essential, even with the most sophisticated automated tools. Users need to understand the underlying principles of finance to make informed decisions, interpret the advice provided by AI, and recognize when human intervention might be necessary. Financial education programs must evolve to include modules on understanding and effectively using automated financial tools, ensuring that individuals are empowered partners in their financial journey, not just passive recipients of automated advice.
By 2026, the role of human financial advisors may shift from transactional tasks to more complex, holistic guidance, focusing on behavioral coaching, intergenerational wealth transfer, and navigating unique life circumstances that automation alone cannot fully address. The synergy between human expertise and automated efficiency will define the future of automation financial wellness . This collaborative model ensures that individuals receive the best of both worlds: the speed and precision of AI combined with the empathy and nuanced understanding of human advisors. It’s about augmenting human capability, not replacing it entirely.
Future Trends: Beyond 2026 in Automation and Financial Wellness
Looking beyond 2026, the integration of automation and personal finance is set to become even more seamless and pervasive. Several emerging trends will further solidify the role of technology in enhancing financial wellness.
Hyper-Personalization and Proactive Financial Health
The future of automation financial wellness lies in hyper-personalization. AI will move beyond generic recommendations to offer highly tailored advice based on an individual’s unique life circumstances, psychological biases, and even emotional responses to financial situations. Imagine an AI that not only knows your spending habits but also understands your financial anxieties and offers strategies to mitigate them, or an AI that can predict a major life event (like a job change or a new family member) and proactively adjust your financial plan.
This level of personalization will be enabled by the increasing integration of various data sources, from health wearables that track stress levels to smart home devices that monitor consumption patterns. Ethical considerations around data usage will, of course, be paramount, but the potential for truly proactive financial health management is immense. These systems will act less like tools and more like personalized financial co-pilots, constantly monitoring, predicting, and advising to optimize an individual’s financial trajectory. They will learn from every interaction, becoming increasingly attuned to individual needs and preferences, making financial planning feel less like a chore and more like an intuitive conversation.
Embedded Finance and Invisible Payments
Embedded finance, where financial services are integrated directly into non-financial platforms, will become more prevalent. Think of buying a car and having the loan application, approval, and payment system seamlessly integrated into the car dealership’s digital platform, all powered by automation. Or imagine an e-commerce site where installment payments are automatically arranged and managed based on your financial profile, without ever leaving the checkout page.
Invisible payments, where transactions occur automatically in the background (e.g., subscription renewals, utility bills), will also expand, freeing up mental bandwidth and reducing the chances of missed payments. While convenient, this trend will necessitate even greater transparency and control mechanisms for users to manage these automated financial flows effectively. The goal is to make financial transactions so frictionless that they become almost imperceptible, allowing individuals to focus on their lives rather than the mechanics of money. This shift will further embed automation financial wellness into the fabric of daily life, making financial management an inherent part of consumption and planning.
Blockchain and Decentralized Finance (DeFi) Integration
Blockchain technology and decentralized finance (DeFi) are also poised to intersect with automation financial wellness in significant ways. Smart contracts can automate financial agreements, ensuring transparency and reducing the need for intermediaries in lending, borrowing, and insurance. While still in its nascent stages for mainstream adoption, the potential for blockchain to create more secure, transparent, and efficient automated financial systems is enormous.
By 2026 and beyond, we might see automated financial tools that leverage DeFi protocols for peer-to-peer lending, yield farming, and decentralized insurance, offering new avenues for wealth creation and risk management. This will require a steep learning curve for many, but the underlying automation will make these complex financial instruments more accessible to the average user. The combination of AI and blockchain could lead to entirely new models of financial services, where trust is built into the protocol rather than relying on centralized institutions. This could open up global financial opportunities and provide unprecedented levels of financial autonomy, further redefining the boundaries of what is possible in personal finance.
Empowering Individuals Through Financial Education and Automation
The success of the automation financial wellness revolution ultimately hinges on empowering individuals to effectively utilize these tools. Financial education must evolve to meet the demands of this new era. It’s no longer enough to teach basic budgeting; individuals need to understand how algorithms work, how to interpret AI-driven advice, and how to protect their digital financial footprint.
Educational initiatives should focus on developing critical thinking skills related to financial technology. This includes understanding the benefits and limitations of various automated tools, recognizing potential biases in algorithms, and making informed decisions about data sharing. Workshops, online courses, and interactive simulations can help individuals gain practical experience with automated financial platforms in a safe environment.
Moreover, financial institutions and fintech companies have a responsibility to design user-friendly interfaces and provide clear, concise explanations of their automated services. Transparency about how algorithms make decisions and how data is used will build trust and encourage wider adoption. The goal is not to replace human understanding with automation but to enhance it, allowing individuals to leverage technology as a powerful ally in their pursuit of financial well-being.
This collaborative approach – between technology developers, educators, and individuals – will ensure that automation truly serves as a force for good in personal finance. By fostering a financially literate and technologically adept population, we can unlock the full potential of automation to create a more equitable, secure, and prosperous financial future for everyone. The continuous feedback loop between user experience and AI development will drive further innovation, making these tools even more responsive and effective. This iterative improvement will ensure that the benefits of automation are continually refined and expanded, making financial wellness an achievable goal for an ever-increasing number of people.
Conclusion: A Brighter Financial Future with Automation
By 2026, the impact of automation on personal financial wellness will be profound and far-reaching. From intelligent budgeting apps and sophisticated robo-advisors to proactive debt management systems and hyper-personalized retirement planning, technology is set to transform how we interact with our money. While challenges related to data security and digital inclusion remain, the overall trajectory points towards a future where financial management is more accessible, efficient, and empowering than ever before.
Embracing these advancements, coupled with a commitment to continuous financial education and robust ethical frameworks, will be key to unlocking the full potential of automation financial wellness . As individuals, understanding and adapting to these changes is not just beneficial; it is essential for securing a resilient and prosperous financial future in an increasingly automated world. The journey towards optimal financial wellness is becoming less about complex calculations and more about smart, automated decisions that align with personal goals and values. The future of finance is here, and it is automated, intelligent, and designed to put you in control.