Achieving Financial Peace of Mind in 2026: 3 Essential Pillars (INSIDER KNOWLEDGE)
Achieving Financial Peace of Mind in 2026: 3 Essential Pillars (INSIDER KNOWLEDGE)
The year 2026 is rapidly approaching, and with it comes an opportunity to reassess and redefine our financial goals. In an ever-evolving global economy, achieving financial peace 2026 requires more than just good intentions; it demands a strategic, disciplined, and informed approach. This comprehensive guide will delve into three essential pillars that, when meticulously applied, can pave your way to genuine financial peace of mind. We’re not just talking about saving money; we’re talking about building a resilient financial ecosystem that can withstand economic fluctuations and support your long-term aspirations. This is insider knowledge, distilled and presented for your benefit.
Pillar 1: Strategic Budgeting and Cash Flow Mastery
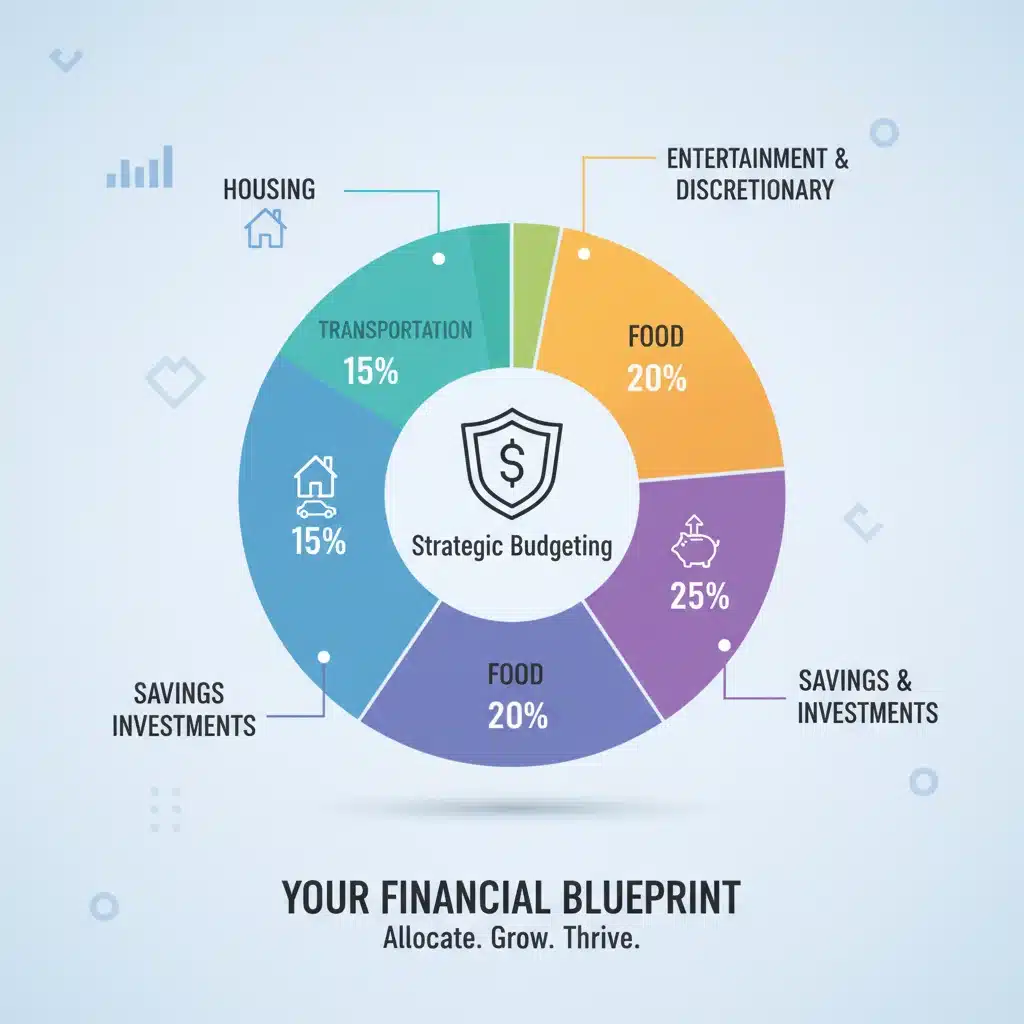
The foundation of any sound financial plan is a well-structured budget. However, we’re not advocating for restrictive, joy-killing budgets. Instead, our focus is on strategic budgeting – a dynamic process that aligns your spending with your values and financial objectives for financial peace 2026. This involves more than just tracking expenses; it’s about mastering your cash flow, understanding where every dollar goes, and consciously directing it towards your goals.
Understanding Your Financial Landscape
Before you can budget effectively, you need a clear picture of your current financial situation. This means gathering all your financial statements: bank accounts, credit card bills, loan statements, and investment portfolios. Categorize your income and expenses meticulously. Tools, whether digital apps or simple spreadsheets, can be invaluable here. The goal is to identify fixed expenses (rent/mortgage, loan payments, insurance) versus variable expenses (groceries, entertainment, dining out). Many people overlook the power of understanding their spending habits; this is the first crucial step towards achieving financial peace 2026.
The 50/30/20 Rule (and its Adaptations)
A popular and effective budgeting framework is the 50/30/20 rule:
- 50% for Needs: This includes housing, utilities, groceries, transportation, insurance, and minimum loan payments. These are non-negotiable expenses required for basic living.
- 30% for Wants: This category covers discretionary spending like dining out, entertainment, hobbies, vacations, and shopping. This is where strategic choices can significantly impact your savings.
- 20% for Savings and Debt Repayment: This portion is dedicated to building an emergency fund, investing for retirement, saving for major purchases, and paying down high-interest debt beyond the minimums.
While the 50/30/20 rule is a great starting point, it’s essential to adapt it to your unique circumstances. For instance, if you live in a high cost of living area, your ‘needs’ might exceed 50%. In such cases, you might need to adjust the ‘wants’ or ‘savings’ percentages, or explore ways to increase your income. The key is flexibility and consistent review. Regularly revisit your budget, ideally monthly, to ensure it still aligns with your income and goals. Strategic budgeting is not a one-time setup; it’s an ongoing dialogue with your money, critical for maintaining financial peace 2026.
Automating Your Savings and Bills
One of the most powerful strategies for cash flow mastery is automation. Set up automatic transfers from your checking account to your savings and investment accounts immediately after your paycheck hits. Treat these transfers like non-negotiable bills. Similarly, automate your bill payments to avoid late fees and manage your cash flow more effectively. This ‘pay yourself first’ approach ensures that your financial goals are prioritized, making your journey towards financial peace 2026 much smoother.
Think of strategic budgeting as building a robust dam. You’re not just stopping the flow of water (money) randomly; you’re directing it purposefully to where it can generate the most benefit, whether that’s powering a turbine (investments) or filling a reservoir (emergency fund). This intentional direction is what sets strategic budgeting apart and makes it a cornerstone of financial peace 2026.
Pillar 2: Diversified Investing for Growth and Stability
Once your budget is in order and you’ve mastered your cash flow, the next critical pillar for financial peace 2026 is intelligent, diversified investing. Simply saving money isn’t enough to outpace inflation or achieve significant wealth growth. Investing allows your money to work for you, compounding over time and building substantial assets. However, ‘intelligent’ investing doesn’t mean chasing speculative trends; it means understanding risk, diversification, and long-term strategy.
Understanding Your Risk Tolerance
Before you invest a single dollar, it’s crucial to understand your personal risk tolerance. Are you comfortable with market fluctuations for the potential of higher returns, or do you prefer a more stable, albeit slower, growth path? Your age, financial goals, and personal circumstances all play a role in determining this. Younger investors with a longer time horizon might opt for more aggressive growth strategies, while those closer to retirement might prioritize capital preservation. Aligning your investments with your risk tolerance is key to avoiding emotional decisions during market downturns, a vital aspect of maintaining financial peace 2026.
The Power of Diversification
Diversification is perhaps the most fundamental principle of intelligent investing. It’s the strategy of spreading your investments across various asset classes, industries, and geographical regions to minimize risk. The old adage, ‘don’t put all your eggs in one basket,’ holds immense truth in the investment world. A well-diversified portfolio might include:
- Stocks (Equities): Representing ownership in companies, offering potential for significant growth but also higher volatility.
- Bonds (Fixed Income): Loans to governments or corporations, generally offering lower returns but also lower risk. They provide stability to a portfolio.
- Real Estate: Can include direct property ownership, real estate investment trusts (REITs), or crowdfunding. Offers potential for appreciation and rental income.
- Commodities: Gold, silver, oil, and agricultural products can act as a hedge against inflation and currency fluctuations.
- Alternative Investments: Such as private equity, hedge funds, or even cryptocurrencies (though these carry higher risk and require careful consideration).
For most individual investors, diversified exchange-traded funds (ETFs) and mutual funds offer an accessible way to achieve broad market exposure without needing to pick individual stocks. These funds often hold hundreds or thousands of underlying securities, instantly diversifying your portfolio. Regular rebalancing of your portfolio, typically once or twice a year, ensures that your asset allocation remains consistent with your risk tolerance and goals, further securing your path to financial peace 2026.
Long-Term Perspective and Avoiding Market Timing
Successful investing for financial peace 2026 and beyond is almost always a long-term endeavor. Attempting to ‘time the market’ – buying low and selling high based on predictions – is notoriously difficult and often leads to worse returns than a consistent, disciplined approach. Instead, focus on dollar-cost averaging, where you invest a fixed amount regularly, regardless of market fluctuations. This strategy allows you to buy more shares when prices are low and fewer when prices are high, averaging out your purchase price over time. Patience and discipline are your greatest allies in the investment world.
Moreover, understand that market corrections and downturns are a normal part of the investment cycle. Rather than panicking, view them as opportunities to buy quality assets at a discount. A long-term perspective and an unwavering commitment to your diversified strategy will help you navigate these periods confidently, ensuring your investments continue to grow towards your goal of financial peace 2026.
Pillar 3: Robust Emergency Fund and Risk Management
The final, yet equally crucial, pillar for achieving financial peace 2026 is the establishment and maintenance of a robust emergency fund, coupled with comprehensive risk management. Life is unpredictable, and unexpected expenses can derail even the most meticulously planned budgets and investment strategies. An emergency fund acts as your financial safety net, protecting your assets and preventing you from incurring high-interest debt when unforeseen events occur.
Building Your Emergency Fund
The general recommendation for an emergency fund is to save 3 to 6 months’ worth of essential living expenses. For those with less stable income or dependents, aiming for 6 to 12 months might be more prudent. This fund should be:
- Liquid: Easily accessible, typically held in a high-yield savings account, money market account, or a short-term certificate of deposit (CD) that allows for early withdrawal without significant penalty.
- Separate: Kept in a separate account from your regular checking and savings accounts to avoid inadvertently spending it.
- Untouched: Used only for true emergencies, such as job loss, unexpected medical bills, major home repairs, or car breakdowns. It is not for vacations, holiday shopping, or a new gadget.
Building this fund takes discipline, especially in the initial stages. Treat it as a non-negotiable expense in your budget, just like your rent or mortgage. Automate transfers to this account to ensure consistent contributions. The peace of mind that comes from knowing you have a financial buffer against life’s curveballs is immeasurable and a direct contributor to financial peace 2026.
Comprehensive Risk Management
Beyond the emergency fund, effective risk management involves protecting yourself against larger, potentially catastrophic financial losses. This primarily comes in the form of adequate insurance coverage:
- Health Insurance: Essential for covering medical emergencies, doctor visits, and prescriptions. A single major illness can wipe out years of savings without proper coverage.
- Auto Insurance: Legally required in most places, it protects you financially in case of accidents, theft, or damage to your vehicle.
- Homeowner’s or Renter’s Insurance: Protects your dwelling and personal belongings against damage, theft, and liability.
- Life Insurance: Particularly important if you have dependents, it provides financial support to your loved ones in the event of your untimely death.
- Disability Insurance: Replaces a portion of your income if you become unable to work due to illness or injury. Often overlooked, this can be a lifeline.
Regularly review your insurance policies to ensure they provide adequate coverage for your current situation. As your life circumstances change (marriage, children, new home, career changes), your insurance needs will also evolve. Being proactively protected against major financial risks is a cornerstone of achieving and maintaining financial peace 2026.
Debt Management and Elimination
While an emergency fund protects against unforeseen expenses, managing and eliminating high-interest debt is crucial for long-term financial stability. Credit card debt, personal loans, and other forms of consumer debt can erode your financial progress quickly. Prioritize paying down these debts, often using strategies like the ‘debt snowball’ (paying off smallest balances first for psychological wins) or the ‘debt avalanche’ (paying off highest interest rates first for mathematical efficiency).
Reducing your debt burden frees up more of your income for savings and investments, significantly accelerating your journey towards financial peace 2026. It also reduces financial stress, allowing you to make clearer, more rational financial decisions.
Bringing It All Together for Financial Peace 2026
Achieving financial peace 2026 isn’t about isolated actions; it’s about the synergistic application of these three pillars. Imagine your financial life as a sturdy three-legged stool. Each leg – strategic budgeting, diversified investing, and a robust emergency fund with risk management – is essential. Remove one, and the stool becomes unstable; remove two, and it topples over entirely.
The Interconnectedness of the Pillars
- Your strategic budget provides the surplus funds necessary for both your emergency fund and your investments. Without a clear understanding and control of your cash flow, neither savings nor investing can be consistently effective.
- Your emergency fund protects your investments. If an unexpected expense arises, you won’t have to sell off investments at an inopportune time, potentially incurring losses or missing out on future growth.
- Your diversified investments ensure that your money grows over time, creating a buffer against inflation and building wealth, which in turn reduces the pressure on your active income and enhances your sense of financial security.
This holistic approach is what defines true financial peace 2026. It’s not just about having money; it’s about having a system in place that manages your money effectively, protects you from financial shocks, and grows your wealth steadily.
Actionable Steps to Begin Today
- Review and Revamp Your Budget: Start by meticulously tracking your income and expenses for a month. Identify areas where you can cut back or reallocate funds according to your values and goals. Implement the 50/30/20 rule as a guideline.
- Automate Your Savings: Set up automatic transfers to your emergency fund and investment accounts immediately after payday. Make saving a priority, not an afterthought.
- Assess Your Investments: Understand your risk tolerance and ensure your portfolio is adequately diversified. If you’re unsure, consider consulting a financial advisor.
- Build/Reinforce Your Emergency Fund: If you don’t have 3-6 months of essential expenses saved, make this your immediate financial priority.
- Review Your Insurance Coverage: Ensure you have adequate health, auto, home/renter’s, life, and disability insurance.
- Tackle High-Interest Debt: Develop a plan to systematically pay down any high-interest consumer debt.
The journey to financial peace 2026 is ongoing, requiring continuous learning, adaptation, and discipline. Economic landscapes shift, personal circumstances change, and market conditions fluctuate. By regularly reviewing your financial plan and making necessary adjustments, you can ensure that these three essential pillars remain strong and supportive.
The Psychological Benefit of Financial Peace
Beyond the tangible benefits of increased wealth and security, achieving financial peace 2026 has profound psychological advantages. Reduced financial stress leads to better overall health, improved relationships, and a greater capacity to focus on other aspects of your life that bring joy and fulfillment. When you’re not constantly worried about money, you free up mental and emotional energy to pursue your passions, spend quality time with loved ones, and contribute meaningfully to your community. This intrinsic value of financial peace is often overlooked but is arguably the most significant reward of diligent financial planning.
Embrace the challenge, commit to these three pillars, and you will not only achieve financial peace 2026 but also lay the groundwork for a lifetime of financial security and freedom. The insider knowledge presented here is your roadmap; now it’s up to you to take the journey.
Author