Master Your Finances: 3-Month Debt Reduction Plan 2026
Master Your Finances: A 3-Month Debt Reduction Plan for 2026
Are you looking to make 2026 the year you finally conquer your debt and achieve true financial freedom? If so, you’ve come to the right place. Debt can feel like a heavy burden, impacting every aspect of your life, from your daily stress levels to your long-term financial goals. But it doesn’t have to be a permanent fixture. With a strategic and disciplined approach, you can significantly reduce your debt and build a more secure financial future. This article outlines a practical, step-by-step debt reduction plan designed to help you make substantial progress in just three months.
The journey to becoming debt-free might seem daunting, but breaking it down into manageable steps can make it achievable. Our debt reduction plan focuses on actionable strategies, giving you the tools and insights you need to take control. We’ll cover everything from understanding your current financial situation to implementing effective payment strategies and maintaining momentum. By the end of this 3-month journey, you’ll not only have less debt but also a stronger financial foundation and a clearer path forward.
Let’s dive into the details and start your transformation towards financial well-being in 2026!
Month 1: The Foundation – Understanding and Strategizing Your Debt Reduction Plan
The first month of your debt reduction plan is all about laying a solid foundation. You can’t effectively fight an enemy you don’t understand, and debt is no different. This phase involves a comprehensive assessment of your financial landscape, followed by the creation of a realistic and actionable budget. This is where you gain clarity and set the stage for success.
Step 1: Get a Clear Picture of Your Debt
Before you can tackle your debt, you need to know exactly what you’re dealing with. Gather all your financial statements for credit cards, loans (personal, auto, student), mortgages, and any other outstanding balances. Create a detailed list that includes:
- Creditor Name: Who do you owe money to?
- Current Balance: How much is owed on each account?
- Interest Rate (APR): What’s the annual percentage rate for each debt? This is crucial for prioritizing.
- Minimum Payment: What’s the smallest amount you must pay each month?
- Due Date: When is each payment due?
Organizing this information will give you a powerful overview of your liabilities. You can use a simple spreadsheet, a notebook, or a dedicated debt management app. The goal is to have all your debt information in one easily accessible place.
Step 2: Assess Your Income and Expenses
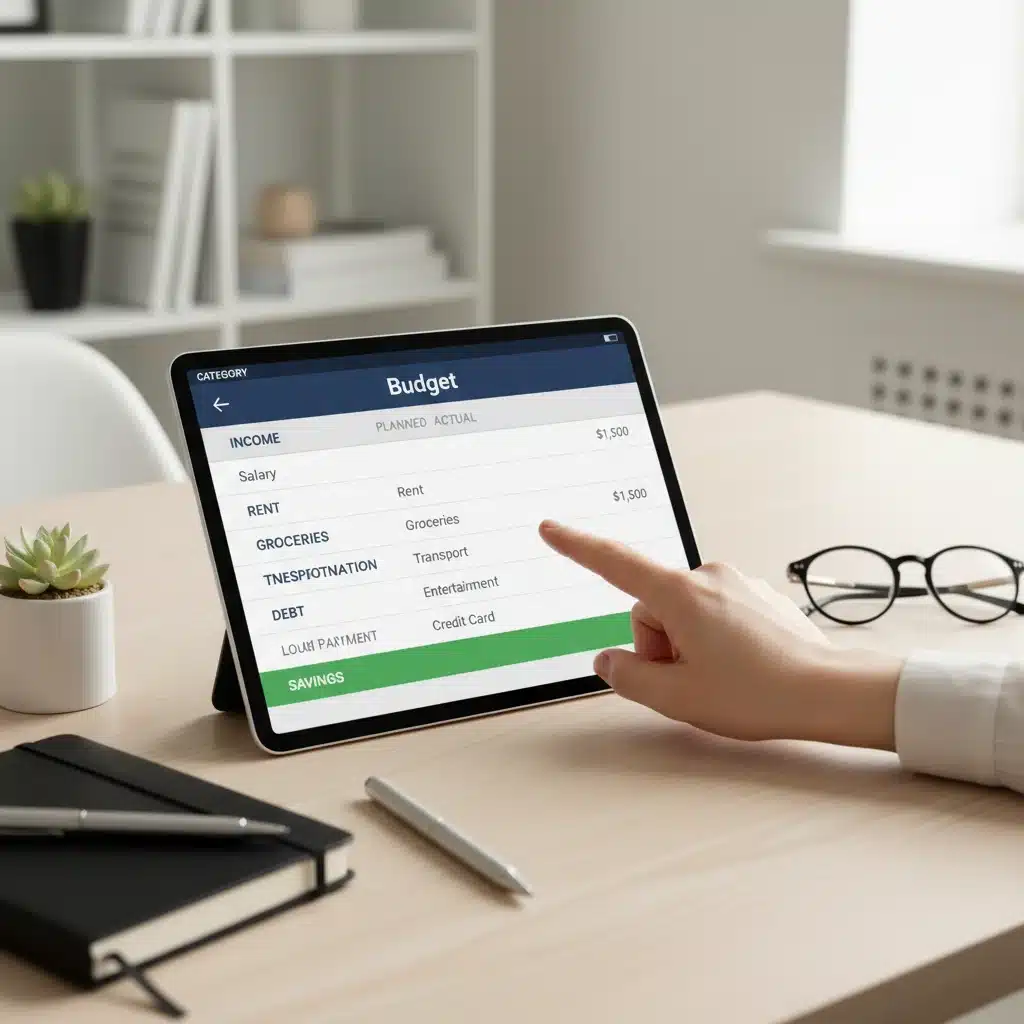
Understanding where your money goes is just as important as knowing what you owe. For one month, meticulously track every dollar you earn and every dollar you spend. This isn’t about judgment; it’s about awareness. Use a budgeting app, a spreadsheet, or even a pen and paper to categorize your expenses. Common categories include:
- Housing (rent/mortgage, utilities)
- Transportation (gas, public transport, car payments)
- Food (groceries, dining out)
- Personal Care (toiletries, haircuts)
- Entertainment
- Debt Payments (minimums)
- Miscellaneous
Once you have a clear picture of your income and expenses, you can identify areas where you might be overspending and where you can cut back to free up more money for your debt reduction plan.
Step 3: Create a Realistic Budget
Now that you know your financial ins and outs, it’s time to create a budget that aligns with your debt reduction goals. A budget is not about deprivation; it’s about intentional spending. Allocate your income to different categories, ensuring that your essential needs are met, and then prioritize debt payments. Look for opportunities to reduce non-essential spending. Can you cut down on dining out? Cancel unused subscriptions? Find cheaper alternatives for services?
The goal is to free up as much extra cash as possible to accelerate your debt reduction plan. Be honest with yourself, but also be realistic. An overly restrictive budget is hard to stick to. Aim for sustainability.
Step 4: Choose a Debt Repayment Strategy
With your debt laid out and your budget in place, you can now choose a targeted repayment strategy. Two popular and effective methods are:
- Debt Snowball Method: List your debts from smallest balance to largest. Pay the minimum on all debts except the smallest one. Throw all extra money at the smallest debt until it’s paid off. Then, take the money you were paying on that debt and add it to the minimum payment of the next smallest debt. This method provides psychological wins as debts are eliminated quickly, building momentum.
- Debt Avalanche Method: List your debts from highest interest rate to lowest. Pay the minimum on all debts except the one with the highest interest rate. Devote all extra funds to that debt until it’s paid off. Then, move to the next highest interest rate debt. This method saves you the most money on interest over time.
Consider which method best suits your personality. If you need quick wins to stay motivated, the snowball method might be better. If you’re disciplined and want to save the most money, the avalanche method is more financially efficient. Either way, having a clear strategy is a cornerstone of any successful debt reduction plan.
Month 2: Acceleration – Implementing Your Debt Reduction Plan
Month two is where you put your carefully crafted plan into action. This is the acceleration phase, focusing on aggressive payments, increasing income, and cutting costs even further. Consistency is key here.
Step 1: Aggressively Attack Your Debts
Now, execute your chosen debt repayment strategy (snowball or avalanche). Make sure you’re consistently paying more than the minimum on your target debt. Automate your minimum payments to avoid late fees, and then manually apply any extra funds to your prioritized debt.
Every extra dollar you put towards your debt now will save you more in interest over the long run. Track your progress. Seeing those balances shrink can be incredibly motivating.
Step 2: Boost Your Income (Even Temporarily)
To accelerate your debt reduction plan, consider ways to temporarily boost your income. This doesn’t mean a career change, but rather finding short-term opportunities to earn extra cash that can be directly applied to your debt. Ideas include:
- Freelancing or Gig Work: Offer skills like writing, graphic design, tutoring, or virtual assistance.
- Selling Unused Items: Declutter your home and sell clothes, electronics, furniture, or collectibles on platforms like eBay, Facebook Marketplace, or local consignment shops.
- Part-Time Job: Even a few hours a week at a part-time job can make a significant difference.
- Overtime at Work: If available and feasible, picking up extra shifts can quickly add to your debt payments.
Every additional dollar earned and applied to debt is a direct hit on your outstanding balances, making your debt reduction plan even more effective.
Step 3: Cut Unnecessary Expenses Further
Revisit your budget from month one. Are there any other areas where you can trim spending? This might involve making tougher choices, but remember, it’s temporary and for a greater financial good. Consider:
- Meal Planning: Drastically reduce dining out and impulse grocery purchases.
- Entertainment: Look for free or low-cost activities.
- Subscriptions: Review and cancel any services you don’t regularly use.
- Transportation: Can you bike or walk more often? Carpool?
Every dollar saved is a dollar that can be redirected to your debt reduction plan. Think creatively about how to reduce your fixed and variable expenses.
Step 4: Negotiate Interest Rates
Don’t be afraid to call your credit card companies or lenders and ask for a lower interest rate. If you have a good payment history, you might be surprised at their willingness to negotiate. A lower interest rate means more of your payment goes towards the principal, accelerating your debt payoff.
Even a small reduction in APR can save you hundreds or thousands of dollars over the life of your debt, making your debt reduction plan more efficient.
Month 3: Momentum and Maintenance – Sustaining Your Debt Reduction Plan
By month three, you should be seeing significant progress. This phase focuses on maintaining momentum, celebrating your wins, and establishing habits that will ensure long-term financial health beyond the initial three months of your debt reduction plan.
Step 1: Review and Adjust Your Budget
At the end of two months, review your budget and your progress. What’s working well? What needs adjustment? Life happens, and your budget should be a living document that adapts to your circumstances. If you’ve paid off a debt, reallocate that payment amount to the next debt in your strategy.
This regular review is vital for ensuring your debt reduction plan remains effective and aligned with your financial reality.
Step 2: Build an Emergency Fund
As you pay down debt, it’s crucial to also start building an emergency fund. This fund acts as a buffer against unexpected expenses (car repairs, medical emergencies, job loss), preventing you from having to rely on credit cards and accumulating new debt. Aim for at least $1,000 to start, and eventually work towards 3-6 months’ worth of living expenses.
Having an emergency fund is a critical component of a sustainable financial future and prevents derailment of your debt reduction plan.
Step 3: Automate Savings and Debt Payments
Once you’ve established your budget and emergency fund goals, automate your financial actions. Set up automatic transfers from your checking to your savings account for your emergency fund. Automate your debt payments, ensuring you pay at least the minimum on time every month, and ideally, automate your extra payments too.
Automation removes the temptation to spend money elsewhere and ensures consistent progress on your debt reduction plan.
Step 4: Celebrate Your Progress and Stay Motivated
Don’t forget to acknowledge your hard work! Celebrate milestones, even small ones. Paid off a credit card? Treat yourself to a small, budget-friendly reward. Seeing your progress can be incredibly motivating. Share your journey with a trusted friend or family member for accountability and support.
Maintaining motivation is crucial for the long-term success of your debt reduction plan.
Advanced Strategies for Your Debt Reduction Plan
Beyond the core 3-month plan, consider these advanced strategies to further accelerate your debt payoff and enhance your financial well-being:
Debt Consolidation or Balance Transfers
If you have multiple high-interest credit card debts, consolidating them into a single loan with a lower interest rate, or transferring balances to a new credit card with a 0% introductory APR, can be a powerful tool. Be cautious, though. Ensure you can pay off the consolidated debt or transferred balance before the introductory period ends, or you might end up paying even more interest. This strategy requires discipline and careful calculation to truly benefit your debt reduction plan.
Working with a Credit Counselor
If your debt feels overwhelming and you’re struggling to make progress on your own, consider consulting a non-profit credit counseling agency. They can help you create a personalized debt management plan, negotiate with creditors on your behalf, and provide valuable financial education. This is a professional step in your debt reduction plan that can offer significant relief and guidance.
Understanding the Psychology of Spending
Debt isn’t always just a numbers game; it often has psychological roots. Take time to understand your spending triggers. Are you an emotional spender? Do you spend to keep up with others? Identifying these patterns can help you develop healthier financial habits and prevent future debt accumulation, solidifying your long-term debt reduction plan.
Common Pitfalls to Avoid in Your Debt Reduction Plan
Even with the best intentions, certain traps can derail your progress. Be aware of these common pitfalls:
- Ignoring Your Budget: A budget is only effective if you stick to it. Regular review and adjustment are crucial.
- Accumulating New Debt: The fastest way to undermine your debt reduction plan is to take on more debt. Avoid new credit card purchases or unnecessary loans.
- Lack of an Emergency Fund: Without savings, unexpected expenses will inevitably lead you back to credit, sabotaging your efforts.
- Giving Up Too Soon: Debt reduction is a marathon, not a sprint. There will be good days and bad days. Stay persistent.
- Not Celebrating Small Wins: Acknowledging progress keeps you motivated. Don’t underestimate the power of positive reinforcement.
Beyond 3 Months: Sustaining Your Financial Health
While this 3-month plan provides a powerful jumpstart, true financial freedom is a continuous journey. After successfully completing this initial phase, continue to:
- Maintain Your Budget: Keep tracking your spending and adjusting your budget as needed.
- Grow Your Emergency Fund: Work towards having 3-6 months of living expenses saved.
- Start Investing: Once high-interest debt is eliminated and your emergency fund is solid, begin investing for your future.
- Set New Financial Goals: Whether it’s saving for a down payment, retirement, or a child’s education, always have something to work towards.
- Educate Yourself: Continue learning about personal finance, investing, and wealth building.
Your debt reduction plan is more than just paying off bills; it’s about building a foundation for a prosperous and stress-free financial life.
Conclusion: Your Path to Financial Freedom in 2026
Embarking on a debt reduction plan requires commitment, discipline, and a clear strategy. This 3-month action plan for 2026 provides a robust framework to help you understand your debt, create an effective budget, implement powerful repayment strategies, and build lasting financial habits.
Remember, every small step you take contributes to a larger victory. By consistently applying the principles outlined in this guide, you will not only significantly reduce your debt but also gain invaluable financial literacy and peace of mind. Start today, stay committed, and make 2026 the year you truly take control of your financial destiny. Your future self will thank you for the hard work and dedication you put into your debt reduction plan.
Author