The Power of a Financial Wellness Budget in 2026: A Step-by-Step Creation Guide (PRACTICAL SOLUTIONS)
In an ever-evolving economic landscape, achieving and maintaining financial stability is more crucial than ever. As we look towards 2026, the concept of a financial wellness budget transcends mere expense tracking; it becomes a holistic strategy for a healthier, more secure future. This isn’t just about cutting costs; it’s about aligning your money with your values, understanding your spending habits, and proactively planning for both expected and unexpected life events. A well-crafted financial wellness budget empowers you to make informed decisions, reduce stress, and ultimately, build a life of financial freedom.
Many people shy away from budgeting, perceiving it as restrictive or complicated. However, when approached with the right mindset and tools, a financial wellness budget can be an incredibly liberating experience. It provides clarity, control, and a clear path toward your aspirations, whether that’s buying a home, saving for retirement, or simply enjoying a comfortable lifestyle without constant financial worry. This comprehensive guide will walk you through every essential step to create an effective financial wellness budget for 2026, offering practical solutions and actionable advice to help you succeed.
The year 2026 brings its own set of unique financial considerations, from technological advancements influencing spending and saving, to potential shifts in global economies. Therefore, your budget needs to be dynamic, adaptable, and forward-thinking. We’ll explore how to not only set up your budget but also how to maintain it, adjust it, and leverage it as a powerful tool for continuous financial growth. Get ready to transform your financial life and embrace true financial wellness.
Understanding Financial Wellness: More Than Just Money
Before diving into the mechanics of creating a financial wellness budget, it’s vital to grasp what financial wellness truly means. It’s not just about having a large bank account balance; it encompasses several key dimensions:
- Financial Security: The ability to meet your current and future financial obligations.
- Financial Freedom of Choice: Having the flexibility to make life choices without undue financial stress.
- Financial Health: A state of being in which your financial resources are adequate to support your lifestyle and goals.
- Financial Literacy: The knowledge and skills to make informed financial decisions.
- Financial Peace of Mind: A sense of calm and confidence about your financial situation.
A financial wellness budget is the strategic roadmap that helps you navigate these dimensions. It’s a proactive approach to managing your resources, ensuring they serve your overall well-being. In 2026, with increasing awareness of mental health and holistic living, integrating financial planning into your overall wellness strategy is paramount. This budget acts as a bridge between your current financial reality and your desired financial future.
Step 1: Assess Your Current Financial Situation (The Foundation)
The first and most critical step in creating any effective financial wellness budget is to gain a clear, honest picture of where you stand financially. This involves a thorough review of your income, expenses, assets, and liabilities. Think of it as a financial health check-up.
Gathering Your Financial Data
- Income Sources: List all sources of income, including your primary salary, freelance work, rental income, investments, and any other regular inflows. Be precise with net income (after taxes and deductions).
- Fixed Expenses: These are costs that typically remain the same each month, such as rent/mortgage payments, loan payments (car, student), insurance premiums, and subscriptions.
- Variable Expenses: These fluctuate monthly and include groceries, utilities (which can vary), transportation, entertainment, dining out, and personal care.
- Assets: Catalog what you own that has monetary value, such as savings accounts, investment portfolios, real estate, and valuable possessions.
- Liabilities: List what you owe, including credit card debt, personal loans, mortgages, and student loans. Note interest rates and minimum payments.
Utilize bank statements, credit card statements, pay stubs, and investment account summaries from the past 3-6 months to get an accurate average. Many banks and financial institutions now offer digital tools to help categorize spending, making this step less daunting. Remember, accuracy here is key to building a realistic financial wellness budget.
Step 2: Define Your Financial Goals for 2026 and Beyond
A budget without goals is like a ship without a rudder. Your financial goals provide the direction and motivation for your financial wellness budget. These goals should be SMART: Specific, Measurable, Achievable, Relevant, and Time-bound.
Examples of Financial Goals:
- Short-Term Goals (1-2 years): Building an emergency fund (3-6 months of living expenses), paying off high-interest credit card debt, saving for a down payment on a car.
- Mid-Term Goals (3-5 years): Saving for a down payment on a home, funding a child’s education, starting a small business, significant debt reduction.
- Long-Term Goals (5+ years): Retirement planning, significant investment growth, purchasing a vacation property, achieving financial independence.
Prioritize your goals. You might have several, but some will be more urgent or impactful than others. Your budget will then be structured to allocate funds towards these priorities. For instance, if paying off high-interest debt is a top priority, your financial wellness budget will reflect aggressive payments towards that liability.
Step 3: Choose Your Budgeting Method
There isn’t a one-size-fits-all approach to budgeting. The best method for your financial wellness budget is the one you can consistently stick with. Here are some popular and effective methods:
Popular Budgeting Methods:
- The 50/30/20 Rule: This simple method allocates 50% of your after-tax income to needs (housing, utilities, groceries), 30% to wants (entertainment, dining out, hobbies), and 20% to savings and debt repayment. It’s a great starting point for many.
- Zero-Based Budgeting: Every dollar of your income is assigned a job (expense, saving, debt). This ensures no money is left unaccounted for and gives you maximum control. It requires more tracking but can be highly effective.
- Envelope System: A classic method, often used with cash, where you allocate specific amounts to different spending categories and place the cash in physical envelopes. When an envelope is empty, spending in that category stops. Digital versions of this exist via apps.
- Paycheck-to-Paycheck Budgeting: For those with fluctuating income or tight budgets, this involves planning how each paycheck will be spent until the next one arrives.
- Value-Based Budgeting: Focuses on aligning spending with your personal values. If travel is important, you might allocate more to a travel fund and less to other ‘wants’ that are less important to you.
Experiment with a few to see which resonates most with your lifestyle and financial personality. The goal is to find a system that feels sustainable, not punitive, as you build your financial wellness budget for 2026.
Step 4: Create Your 2026 Financial Wellness Budget
Now it’s time to put it all together. Based on your income assessment, financial goals, and chosen budgeting method, you can start building your actual budget.
Practical Steps for Budget Creation:
- List All Income: Start with your total net monthly income.
- Categorize and List Expenses: Based on your past spending data, categorize all your expenses (fixed and variable). Be realistic. Don’t underestimate how much you spend on certain items.
- Allocate Funds to Categories: Assign a specific amount of money to each expense category. This is where your chosen budgeting method comes into play. For example, if using the 50/30/20 rule, ensure your ‘needs’ don’t exceed 50% of your income.
- Prioritize Savings and Debt Repayment: Make these non-negotiable line items in your budget, just like rent or utilities. Ideally, you should ‘pay yourself first’ by setting aside savings before you spend on wants.
- Factor in Irregular Expenses: Don’t forget annual costs like car registration, holiday gifts, or yearly subscriptions. Create a sinking fund (a separate savings pot) for these.
- Review and Adjust: Once you’ve drafted your budget, review it to ensure your total allocated expenses and savings do not exceed your total income. If they do, identify areas where you can cut back, starting with variable expenses.
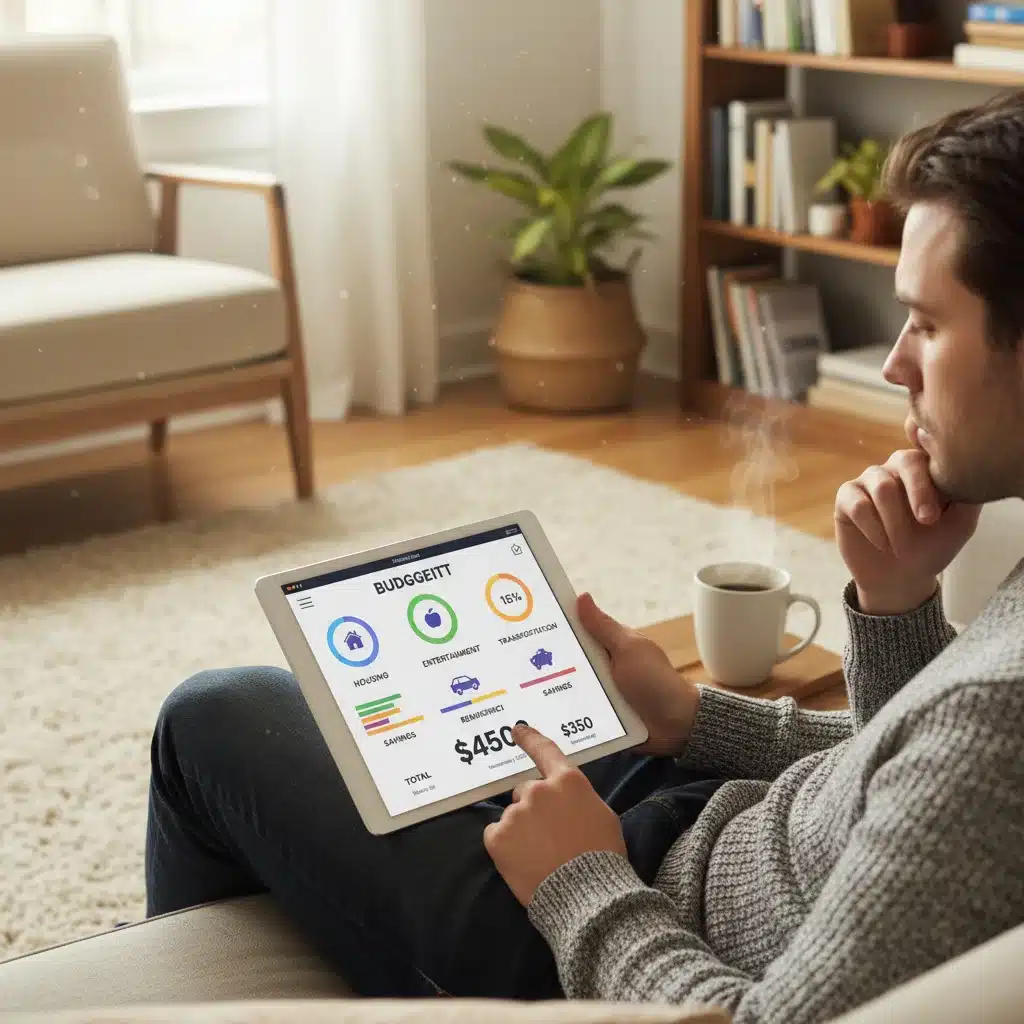
Utilize spreadsheets (Google Sheets, Excel), budgeting apps (You Need A Budget, Mint, Personal Capital), or even pen and paper. The tool is less important than the consistent application of the process. Your financial wellness budget should be a living document.
Step 5: Track Your Spending (The Accountability Factor)
Creating the budget is only half the battle; tracking your spending is where the rubber meets the road. This step ensures you adhere to your financial wellness budget and helps you identify areas for improvement.
Effective Spending Tracking Strategies:
- Daily Check-ins: Make it a habit to log your expenses daily. This prevents you from forgetting transactions and helps you stay aware of your spending.
- Automate Where Possible: Link your bank accounts and credit cards to budgeting apps. Many apps automatically categorize transactions, saving you time and effort.
- Keep Receipts: For cash transactions, keep receipts and log them later.
- Be Honest: Don’t fudge numbers or ignore spending. The more honest you are with your tracking, the more effective your financial wellness budget will be.
- Identify Overspending Triggers: Tracking helps you spot patterns. Do you always overspend on dining out on Fridays? Knowing this allows you to create strategies to curb it.
Consistent tracking provides invaluable insights into your financial habits and is essential for the long-term success of your financial wellness budget. It transforms abstract numbers into tangible realities.
Step 6: Regular Review and Adjustment (Staying Flexible)
Life is dynamic, and so should your financial wellness budget. What works perfectly in January might need tweaking by June. Regular review and adjustment are crucial for its continued effectiveness.
When and How to Review:
- Weekly Check-ins: Briefly review your spending against your budget categories. Are you on track? Do any categories need immediate attention?
- Monthly Deep Dive: At the end of each month, compare your actual spending to your budgeted amounts for every category. Celebrate successes, identify areas of overspending, and understand why discrepancies occurred.
- Quarterly/Annually Reassessment: Life events (new job, marriage, children, moving, economic changes) necessitate a more significant review of your entire financial wellness budget. Re-evaluate your goals, income, and major expenses. Adjust your allocations as needed.
- Embrace Imperfection: Don’t get discouraged if you don’t stick to your budget perfectly every month. The goal is progress, not perfection. Learn from your mistakes and adjust.
This iterative process ensures your financial wellness budget remains relevant and supportive of your evolving financial goals and life circumstances throughout 2026 and beyond.
Step 7: Automate Your Savings and Investments (Future-Proofing Your Finances)
One of the most powerful strategies for building a strong financial wellness budget is to automate your savings and investments. This removes the temptation to spend money that should be saved.
How to Automate:
- Automatic Transfers: Set up automatic transfers from your checking account to your savings account, emergency fund, and investment accounts (e.g., 401k, IRA, brokerage account) on payday.
- Direct Deposit Allocation: Many employers allow you to split your direct deposit, sending a portion directly to a savings or investment account.
- Use Robo-Advisors: Services like Betterment or Acorns can automate your investments, often with low fees and diversified portfolios.
- Round-Up Apps: Apps like Acorns round up your purchases to the nearest dollar and invest the difference. While small, these can add up over time.
Automating your financial contributions ensures that your long-term goals are consistently being funded, making your financial wellness budget a powerful engine for wealth creation.
Step 8: Build an Emergency Fund (Your Financial Safety Net)
An emergency fund is a cornerstone of financial wellness. It’s a dedicated savings account for unexpected expenses like job loss, medical emergencies, or major home/car repairs. Without it, one unforeseen event can derail your entire financial wellness budget.
Emergency Fund Best Practices:
- Aim for 3-6 Months of Living Expenses: This is the generally recommended amount. If you have an unstable income or dependents, aim for closer to 6-12 months.
- Keep it Separate and Accessible: Store your emergency fund in a high-yield savings account that is separate from your checking account but easily accessible when needed.
- Prioritize Building It: Before tackling other savings goals (beyond employer-matched 401k), make building your emergency fund a top priority in your financial wellness budget.
- Replenish When Used: If you dip into your emergency fund, make it a priority to replenish it as quickly as possible.
Having a robust emergency fund provides immense peace of mind and is a critical component of true financial wellness.
Step 9: Strategize Debt Management (Liberating Your Future)
High-interest debt can be a significant drain on your financial resources and a major impediment to achieving financial wellness. Your financial wellness budget must include a clear strategy for debt repayment.
Debt Repayment Strategies:
- Debt Snowball Method: Pay off your smallest debt first, then roll that payment into the next smallest debt. This provides psychological wins.
- Debt Avalanche Method: Pay off debts with the highest interest rates first. This saves you the most money in interest over time.
- Consolidation or Refinancing: Explore options to consolidate high-interest debts into a single loan with a lower interest rate, potentially reducing your monthly payments and overall interest paid.
- Negotiate with Creditors: If you’re struggling, contact your creditors. They may be willing to work with you on payment plans or reduced interest rates.
Allocate a dedicated portion of your financial wellness budget to debt repayment beyond minimum payments. The sooner you eliminate high-interest debt, the more money you’ll have available for savings and investments.
Step 10: Invest in Financial Education (Knowledge is Power)
The financial world is constantly changing. To maintain and improve your financial wellness budget, continuous learning is essential. Financial literacy empowers you to make smarter decisions and adapt to new challenges and opportunities in 2026.
Ways to Boost Your Financial Literacy:
- Read Books and Blogs: There’s a wealth of information available on personal finance, investing, and budgeting.
- Listen to Podcasts: Many financial experts share valuable insights through podcasts.
- Attend Webinars and Workshops: Many financial institutions and non-profits offer free educational resources.
- Follow Reputable Financial Advisors: Even if you don’t hire one, many advisors share general tips and market insights.
- Understand Economic Trends: Stay informed about inflation, interest rates, and other macroeconomic factors that can impact your budget and investments.
By continually educating yourself, you ensure your financial wellness budget is not just a static plan but a dynamic strategy informed by the latest knowledge and best practices.
Common Pitfalls to Avoid in Your Financial Wellness Budget
Even with the best intentions, people often encounter challenges when budgeting. Being aware of these pitfalls can help you navigate them effectively:
- Unrealistic Expectations: Don’t cut expenses so drastically that your budget becomes unsustainable. Start small and make gradual improvements.
- Ignoring Small Expenses: The ‘latte factor’ is real. Small, frequent purchases can add up significantly. Track everything.
- Lack of Flexibility: Life happens. An overly rigid budget is destined to fail. Build in a ‘miscellaneous’ or ‘buffer’ category.
- Comparison to Others: Your financial journey is unique. Don’t compare your budget or financial progress to others. Focus on your goals.
- Giving Up After a Slip-Up: One bad spending day or week doesn’t ruin your entire budget. Get back on track immediately.
- Not Reviewing Regularly: A static budget quickly becomes irrelevant. Consistent review and adjustment are key.
- Lack of Communication (for couples): If you’re in a partnership, open and honest communication about money is vital for a shared financial wellness budget.
By proactively addressing these common issues, you significantly increase the chances of long-term success with your financial wellness budget.
Leveraging Technology for Your 2026 Financial Wellness Budget
In 2026, technology offers an array of tools to simplify and optimize your budgeting process. Embrace these innovations to make managing your financial wellness budget more efficient and less burdensome.
Technological Aids:
- Budgeting Apps: As mentioned, Mint, YNAB (You Need A Budget), Personal Capital, and PocketGuard are popular choices that offer features like transaction categorization, goal tracking, and net worth analysis.
- Spreadsheet Software: Google Sheets and Microsoft Excel offer powerful customization for those who prefer a hands-on approach. There are many free templates available.
- Investment Platforms: Robo-advisors (Betterment, Wealthfront) and traditional brokerage apps (Fidelity, Vanguard) make investing accessible and often automated.
- Banking Apps: Most modern banking apps provide spending insights, categorization, and even budgeting tools directly within their interface.
- Expense Trackers: Simple apps dedicated solely to logging expenses can be useful for quick data entry on the go.
The right tools can turn the daunting task of budgeting into an intuitive and even enjoyable part of your financial routine, reinforcing your commitment to your financial wellness budget.
The Psychological Benefits of a Financial Wellness Budget
Beyond the tangible monetary gains, a well-managed financial wellness budget offers profound psychological benefits:
- Reduced Stress and Anxiety: Knowing where your money goes and having a plan dramatically lowers financial worries.
- Increased Confidence: Taking control of your finances empowers you and boosts self-assurance.
- Improved Relationships: Financial transparency and shared goals can strengthen relationships with partners and family.
- Greater Sense of Control: You’re no longer a passenger in your financial life; you’re the driver.
- Enhanced Decision-Making: With a clear financial picture, you can make better, more informed choices about spending and saving.
- Achieving Goals: The satisfaction of reaching financial milestones, big or small, is incredibly motivating and rewarding.
These benefits underscore why a financial wellness budget is not just about numbers, but about enriching your entire quality of life.
Conclusion: Your Path to Financial Wellness in 2026
Creating and maintaining a financial wellness budget in 2026 is one of the most impactful steps you can take towards securing your financial future and enhancing your overall well-being. It’s a journey that requires commitment, discipline, and a willingness to learn and adapt. By following this step-by-step guide – from assessing your current situation and defining your goals to choosing a budgeting method, tracking expenses, and regularly reviewing your progress – you are building a robust framework for financial success.
Remember that a budget is not a straitjacket; it’s a tool for empowerment. It gives you the clarity to make intentional financial decisions, the control to steer clear of debt, and the foresight to plan for a prosperous future. Embrace the practical solutions offered here, leverage the power of technology, and commit to continuous financial education. The rewards of a well-managed financial wellness budget extend far beyond your bank account, touching every aspect of your life with peace of mind and newfound freedom. Start today, and make 2026 the year you truly master your money and achieve lasting financial wellness.